Sample Tennessee estate accounting
Estate of Jesse L. Madeup (fictional), Deceased. Formatted to the structure of the Tennessee accounting (elements of Tenn. Code §30-2-601). Fictional data throughout.
- Total charges
- $344,889.30
- Total credits
- $344,889.30
- Difference
- $0.00
- Period
- Feb 1, 2025 to Jan 31, 2026
What's in this accounting
27 transactions from 12 fictional statements (CSV) on 1 account, read, categorized, reconciled to each closing balance and rendered by Summafolio. 1 beneficiary; principal and income kept separately. 21 PDF pages (16 schedules); the workbook has the same schedules with live formulas.
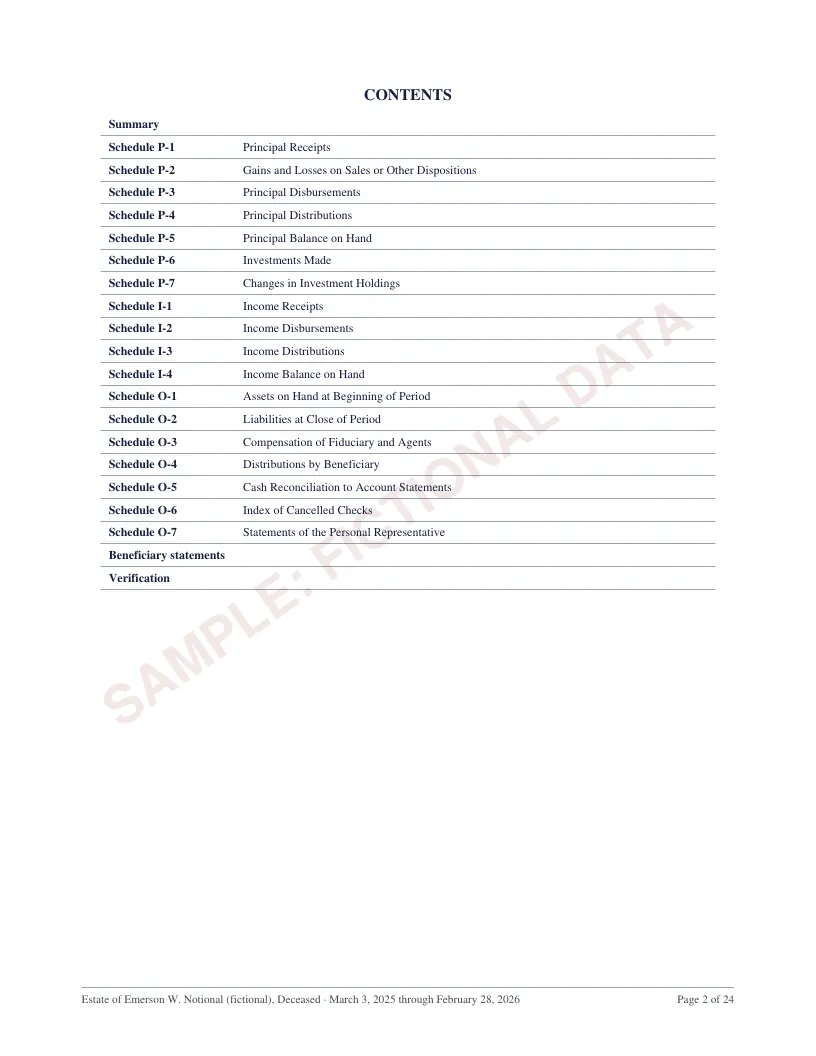
| Schedule | Title | Entries |
|---|---|---|
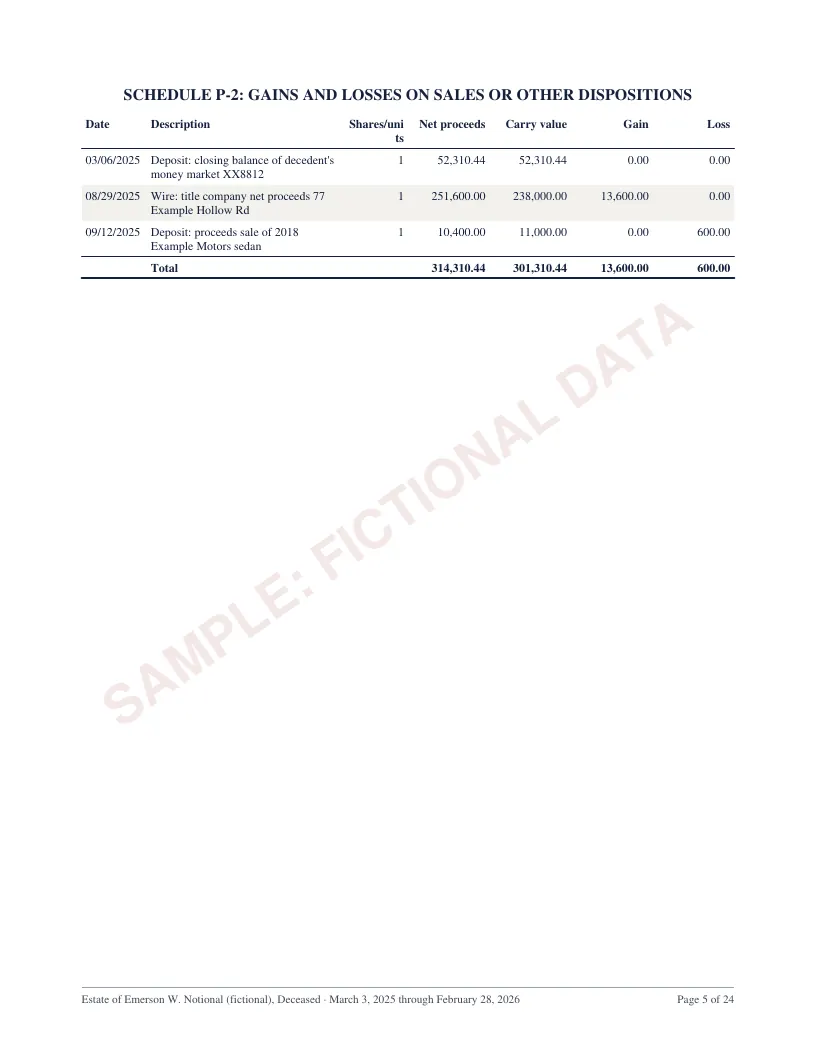
| P-2 | Gains and Losses on Sales or Other Dispositions | 2 |
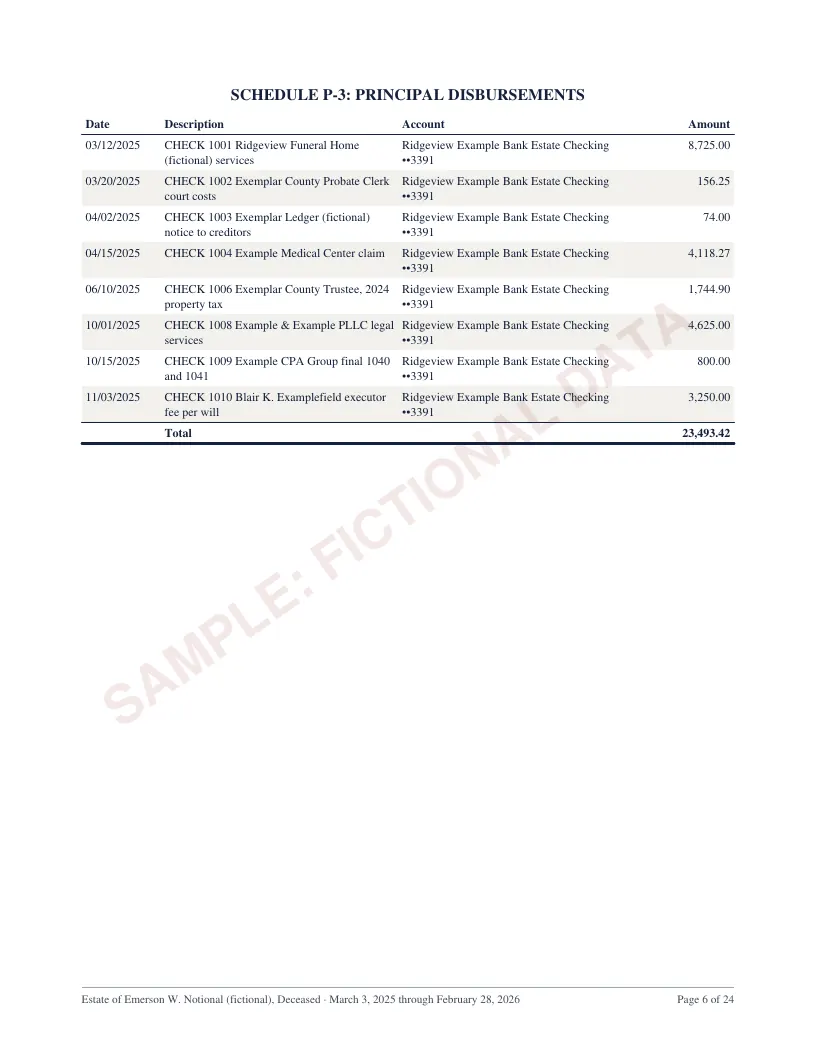
| P-3 | Principal Disbursements | 3 |
| P-4 | Principal Distributions | 1 |
| P-5 | Principal Balance on Hand | 1 |
| I-1 | Income Receipts | 19 |
| I-2 | Income Disbursements | 3 |
| I-4 | Income Balance on Hand | 1 |
| O-1 | Assets on Hand at Beginning of Period | 3 |
| O-4 | Distributions by Beneficiary | 1 |
| O-5 | Cash Reconciliation to Account Statements | 1 |
Schedules with no entries in this sample, left out of the table: P-1, P-6, P-7, I-3, O-2, O-3. They are still in the PDF and workbook.
How to read the summary
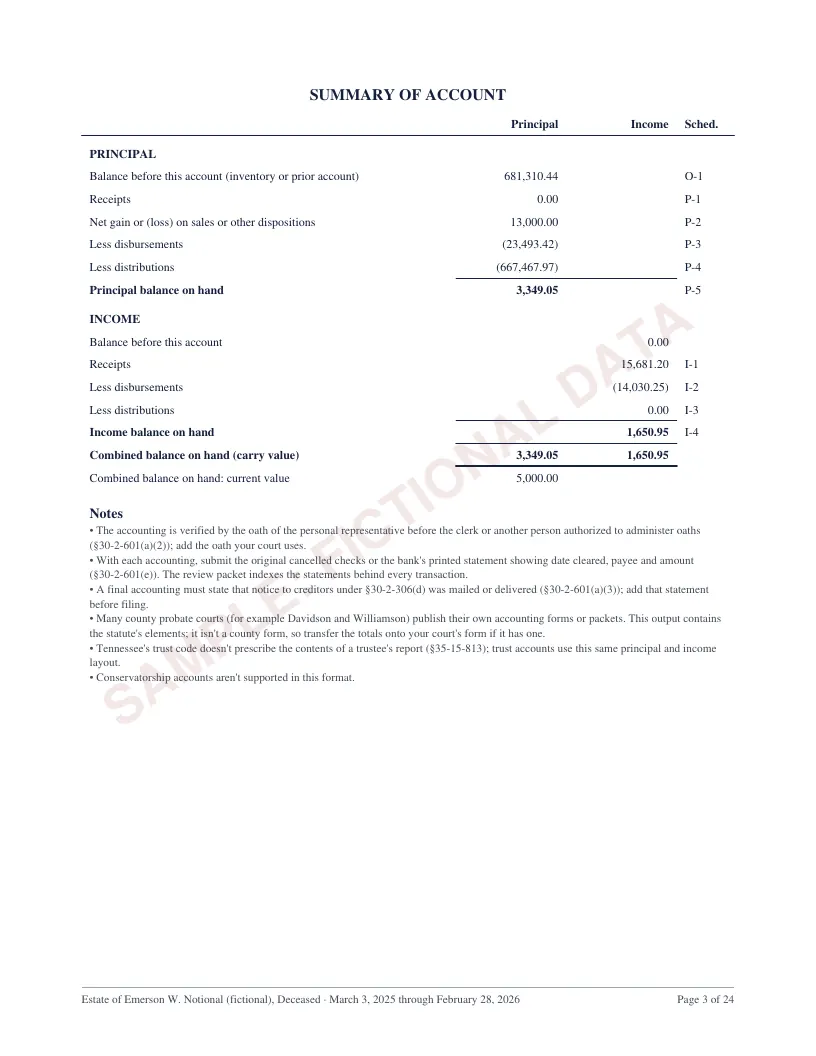
Tenn. Code Ann. §30-2-601(a)(2) says an accounting states all receipts, disbursements and distributions of principal and income for the period and the remaining assets. The summary runs principal and income side by side, and each line points to the schedule that itemizes it.
This sample contains the statute's elements. It isn't a county form: many Tennessee probate courts publish their own accounting forms, so transfer the totals onto your court's form if it has one. Submit the bank statements or cancelled checks §30-2-601(e) asks for; the review packet indexes them.
| Summary line | Principal | Income | Sched. |
|---|---|---|---|
| PRINCIPAL | |||
| Balance before this account (inventory or prior account) | 315,540.10 | O-1 | |
| Receipts | 0.00 | P-1 | |
| Net gain or (loss) on sales or other dispositions | 15,550.00 | P-2 | |
| Less disbursements | (14,420.00) | P-3 | |
| Less distributions | (250,000.00) | P-4 | |
| Principal balance on hand | 66,670.10 | P-5 | |
| INCOME | |||
| Balance before this account | 0.00 | ||
| Receipts | 12,999.20 | I-1 | |
| Less disbursements | (11,675.44) | I-2 | |
| Less distributions | 0.00 | I-3 | |
| Income balance on hand | 1,323.76 | I-4 | |
| Combined balance on hand (carry value) | 66,670.10 | 1,323.76 | |
| Combined balance on hand: current value | 67,993.86 | ||
The §30-2-601 elements in this sample
- Receipts, disbursements and distributions of principal: no new principal receipts (P-1), $15,550.00 net gain on the sale of securities (P-2), $14,420.00 of funeral, medical and legal payments (P-3) and a $250,000.00 distribution (P-4).
- The same for income: $12,999.20 of rent and bank interest (I-1), $11,675.44 of property tax, a rental repair and legal fees (I-2), and no income distributions (I-3).
- The remaining assets: $66,670.10 of principal (P-5) and $1,323.76 of income (I-4) at carry value; $67,993.86 at current value.
- The oath: the verification page is left for signature. §30-2-601(a) requires verification under oath before the clerk or another person authorized to administer oaths.
This is the same fictional estate as the Texas sample, but allocated differently: there every receipt stays in principal, here rent and interest are carried as income and some expenses are charged to income. Check each allocation against Tennessee's principal and income act (title 35, chapter 6) before you file.
What to add before filing
On a final accounting, the statement that notice to creditors was mailed or delivered (§30-2-601(a)(3)); the cancelled checks or bank statements that §30-2-601(e) calls for; and, if your county publishes an accounting form, the totals transferred onto it.
Related
First 6 pages of 21