Sample Nevada trust account
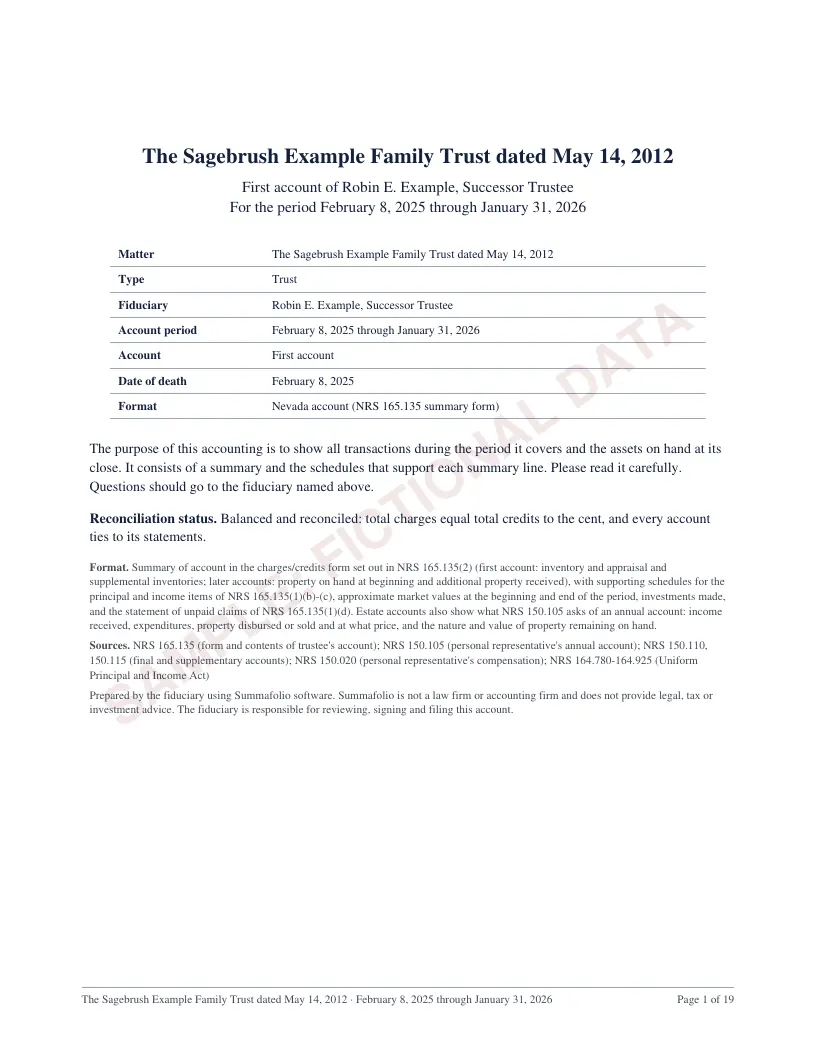
The Silver Example Living Trust dated March 3, 2009. Formatted to the structure of the Nevada account (NRS 165.135 summary form). Fictional data throughout.
- Total charges
- $1,534,485.48
- Total credits
- $1,534,485.48
- Difference
- $0.00
- Period
- Dec 12, 2024 to Dec 31, 2025
What's in this accounting
76 transactions from 25 fictional statements (OFX, PDF) on 2 accounts, read, categorized, reconciled to each closing balance and rendered by Summafolio. 3 beneficiaries; one fund, no principal and income split. 19 PDF pages (13 schedules); the workbook has the same schedules with live formulas.
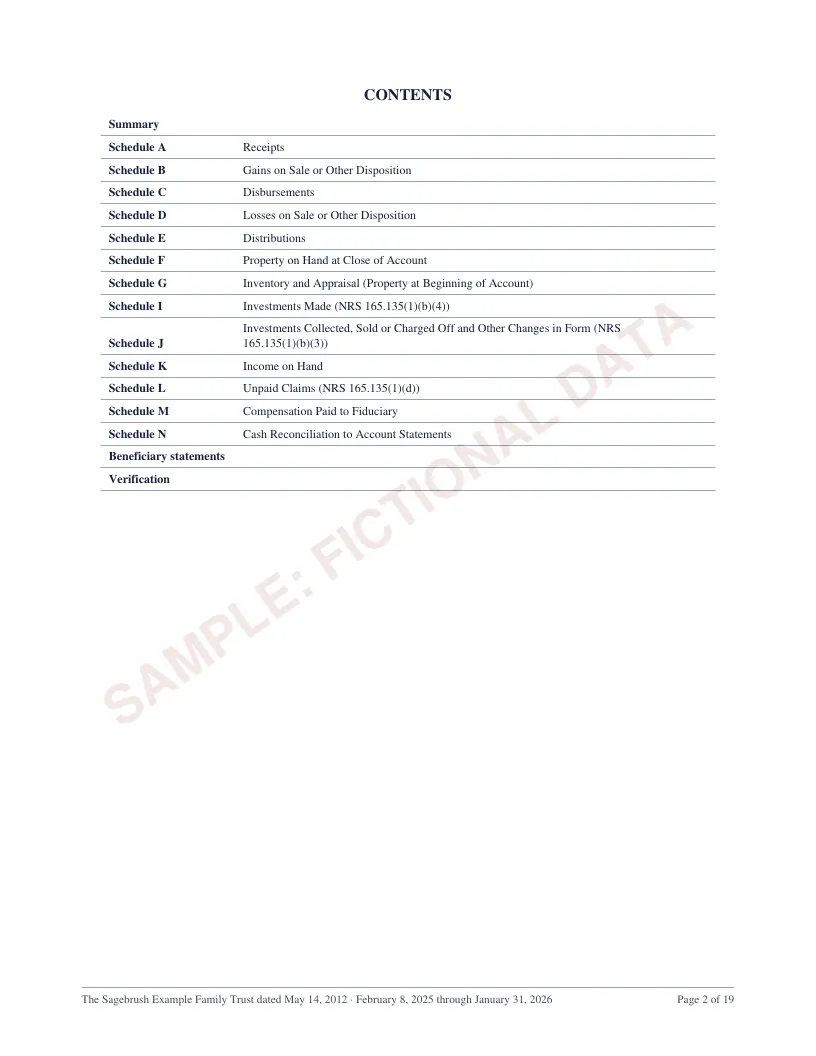
| Schedule | Title | Entries |
|---|---|---|
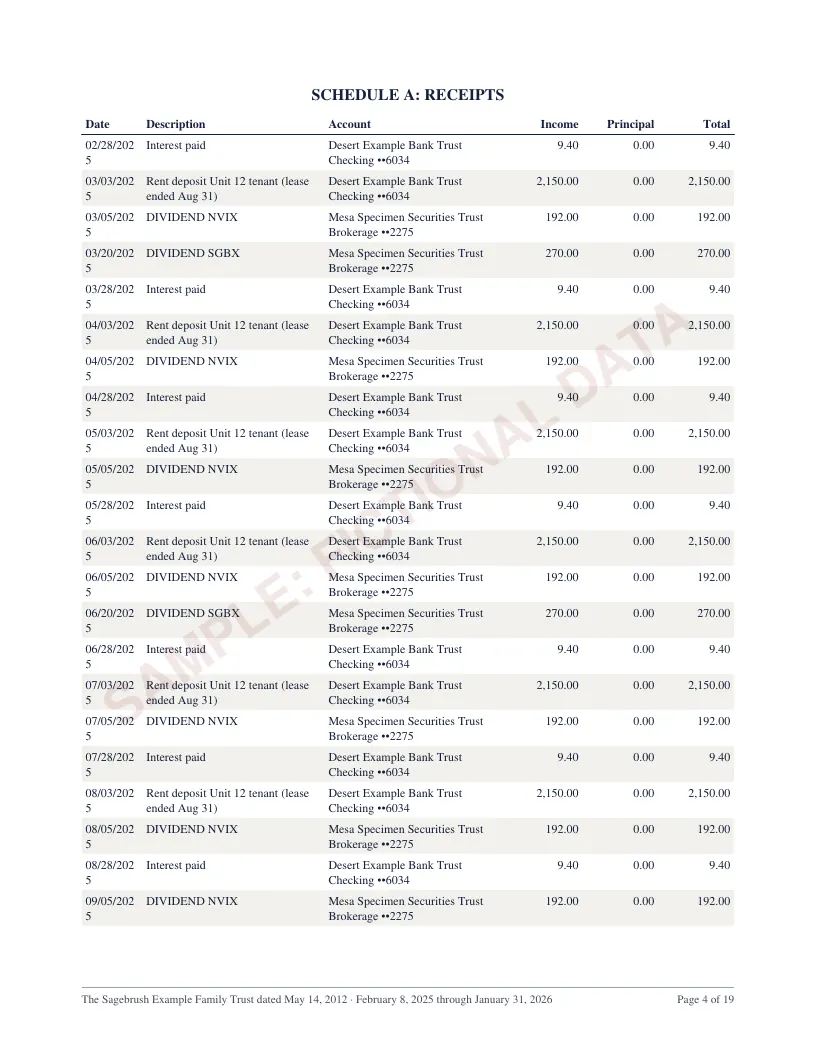
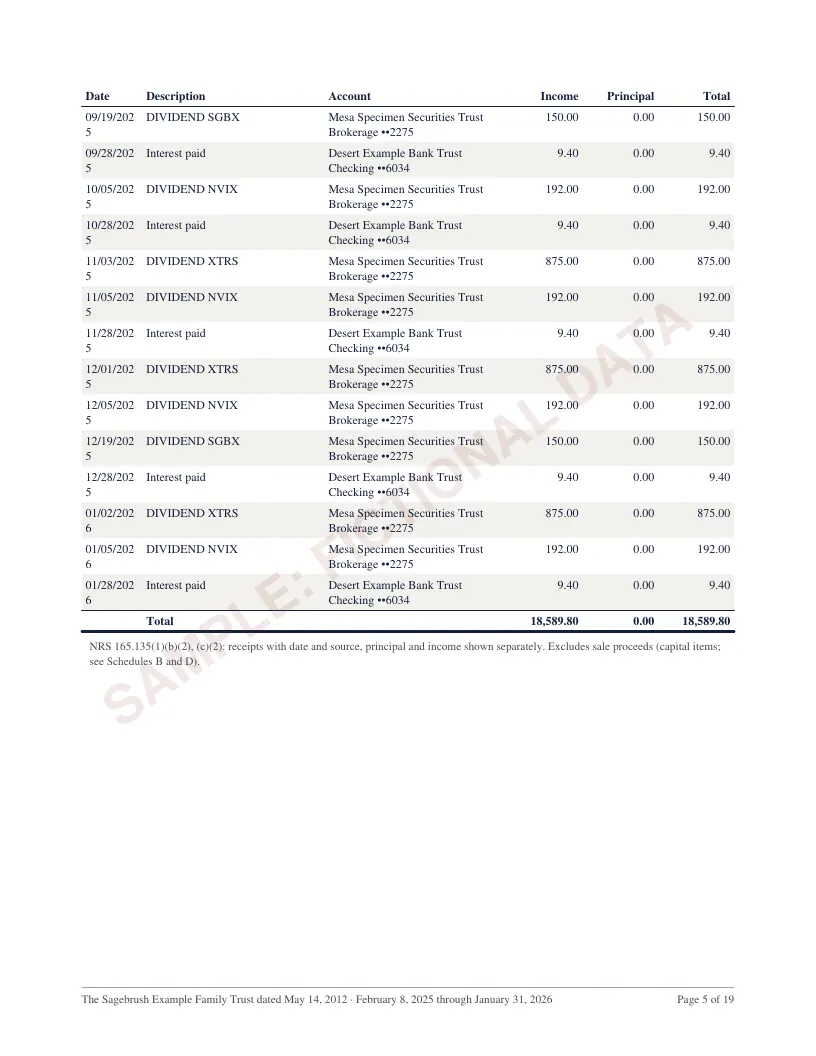
| A | Receipts | 40 |
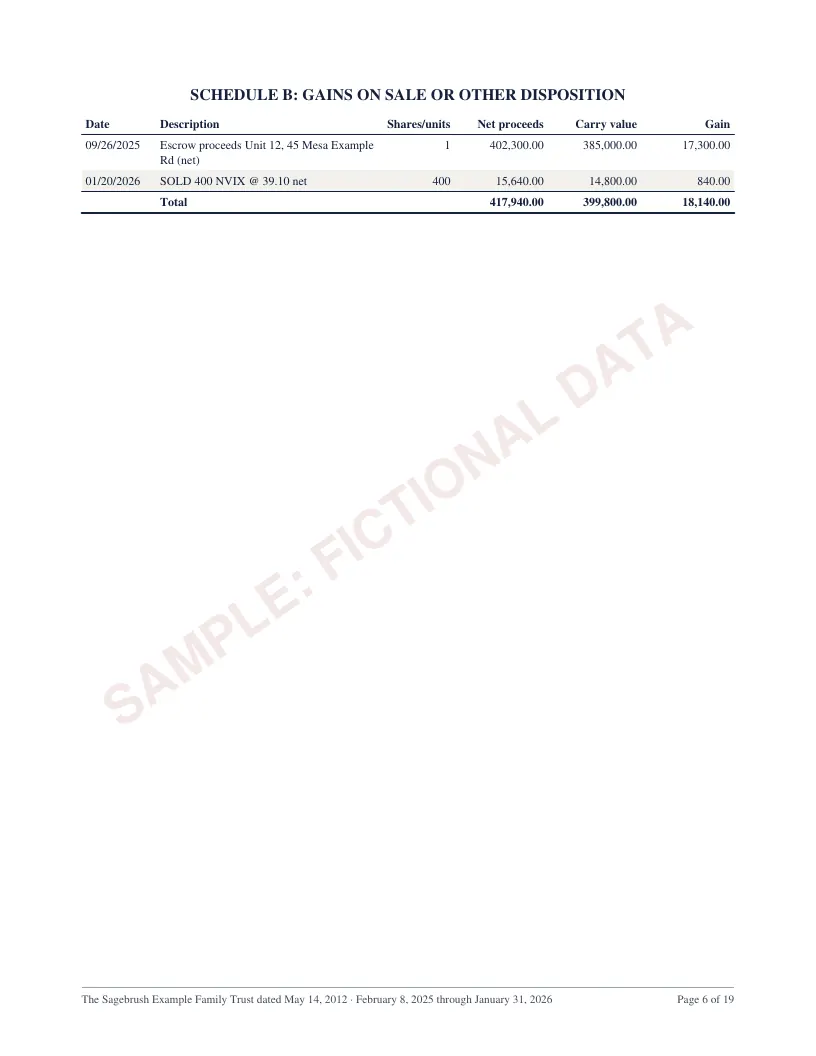
| B | Gains on Sale or Other Disposition | 2 |
| C | Disbursements | 22 |
| D | Losses on Sale or Other Disposition | 2 |
| E | Distributions | 7 |
| F | Property on Hand at Close of Account | 7 |
| G | Inventory and Appraisal (Property at Beginning of Account) | 8 |
| I | Investments Made (NRS 165.135(1)(b)(4)) | 1 |
| J | Investments Collected, Sold or Charged Off and Other Changes in Form (NRS 165.135(1)(b)(3)) | 4 |
| K | Income on Hand | 2 |
| L | Unpaid Claims (NRS 165.135(1)(d)) | 1 |
| M | Compensation Paid to Fiduciary | 1 |
| N | Cash Reconciliation to Account Statements | 2 |
How to read the summary
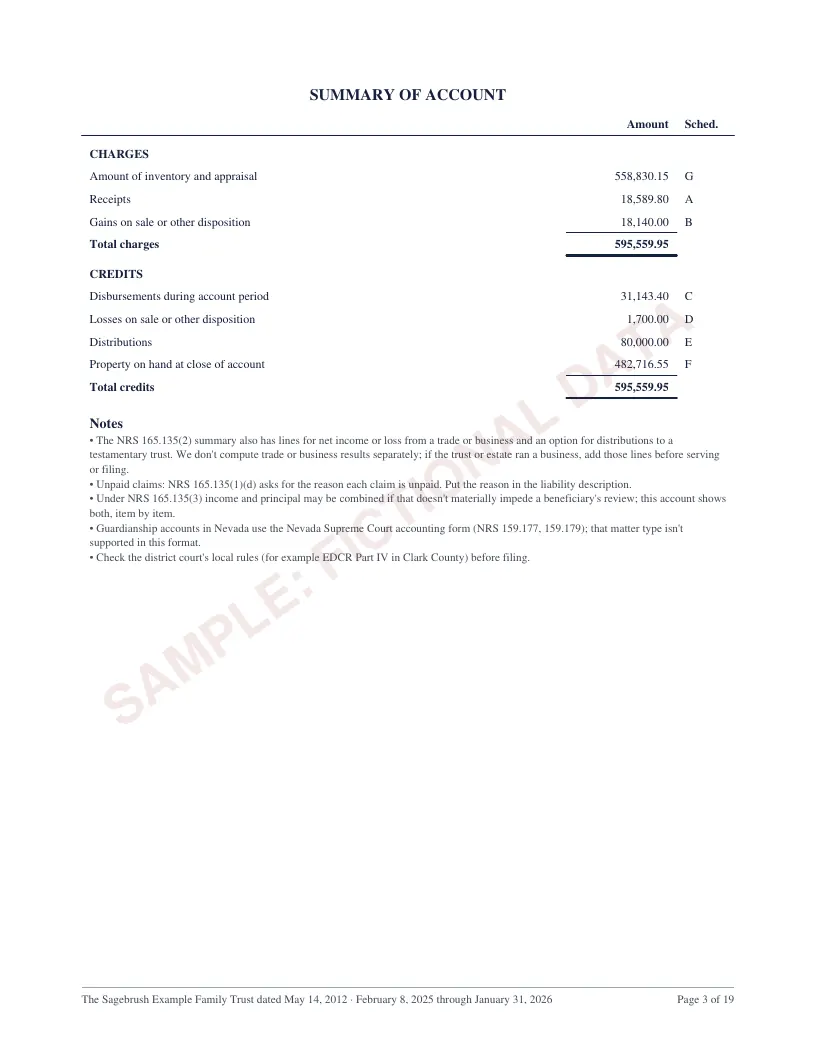
The summary uses the charges and credits form that NRS 165.135(2) sets out. Because this is a first account, the trustee is charged with the amount of the inventory and appraisal (Schedule G), receipts (A) and gains on sale (B), and credited with disbursements (C), losses (D), distributions (E) and the property on hand at the close (F). Total charges equal total credits.
The schedules after the summary give the items NRS 165.135(1) lists: property at the beginning and end with approximate market values (current value column), investments made (I), investments sold or changed in form (J), income on hand (K) and unpaid claims (L). This trust ran no business, so the summary's trade-or-business lines aren't needed; we don't compute those lines for any trust.
| Summary line | Amount | Sched. |
|---|---|---|
| CHARGES | ||
| Amount of inventory and appraisal | 1,511,923.37 | G |
| Receipts | 17,596.11 | A |
| Gains on sale or other disposition | 4,966.00 | B |
| Total charges | 1,534,485.48 | |
| CREDITS | ||
| Disbursements during account period | 63,180.51 | C |
| Losses on sale or other disposition | 14,260.00 | D |
| Distributions | 315,000.00 | E |
| Property on hand at close of account | 1,142,044.97 | F |
| Total credits | 1,534,485.48 | |
How it differs from the California sample
The California sample is built from the same fictional trust, so the totals match. The Nevada account labels the opening line as the amount of the inventory and appraisal and follows NRS 165.135(1) for the other schedules: investments made get their own schedule (I) rather than sitting with the changes in form, as they do under California's §1063(b); income on hand is shown separately (K); and unpaid claims (L) carry the reason each is unpaid, where California's §1063(g) schedule lists liabilities.
Related
First 6 pages of 19